AI search optimization for banks works when product pages state exact, compliance-approved terms in plain text: rate ranges, fees, APR, eligibility and the date they apply from. AI answers quote specific, checkable statements. Hedged marketing copy gives them nothing to quote, so they cite aggregators instead. Your Key Fact Statement is already the most citable thing you own.
When a salaried customer in Indore asks ChatGPT or AI Overviews about personal loan processing fees, the answer names sources. If your bank isn’t one, an aggregator is, possibly quoting last quarter’s numbers.
For an enterprise bank, that is more than lost traffic. It is a third party explaining your pricing to your borrower, in a channel you don’t monitor, possibly wrongly. That is a brand problem and a conduct problem.
This guide is about AEO/GEO for banks in India. AEO/GEO (Answer Engine Optimisation and Generative Engine Optimisation) is the work of making your own pages the source AI systems quote. My position: the compliance process marketing teams treat as a brake is what makes bank content citable.
Why is compliance-reviewed content more citable than marketing copy?
Because compliance review forces the exact quality AI answers reward: specific, attributable, consistent statements. “Processing fee up to 2% of loan amount plus GST, as on 1 September 2026” can be quoted. “Attractive rates, T&C apply” cannot.
The mechanism is retrieval. Answer engines split pages into passages, match them to the question, then write an answer grounded in the ones they picked. Google says its AI features may use “query fan-out”, issuing several related searches across subtopics (Google Search Central). One home loan question becomes sub-queries on rate, processing fee, prepayment charges and eligibility. Each needs a passage that contains the answer. A KFS-level fee table answers most of them in one place. Copy written to avoid commitment answers none.
The line other agencies will argue with: in banking, your compliance team is not the bottleneck to AI visibility; your marketing copy is. I used to treat legal review as the delay to route around. I changed my mind after comparing which bank pages got quoted and which didn’t.
What do AI Overviews, ChatGPT and Perplexity need from a bank’s page?
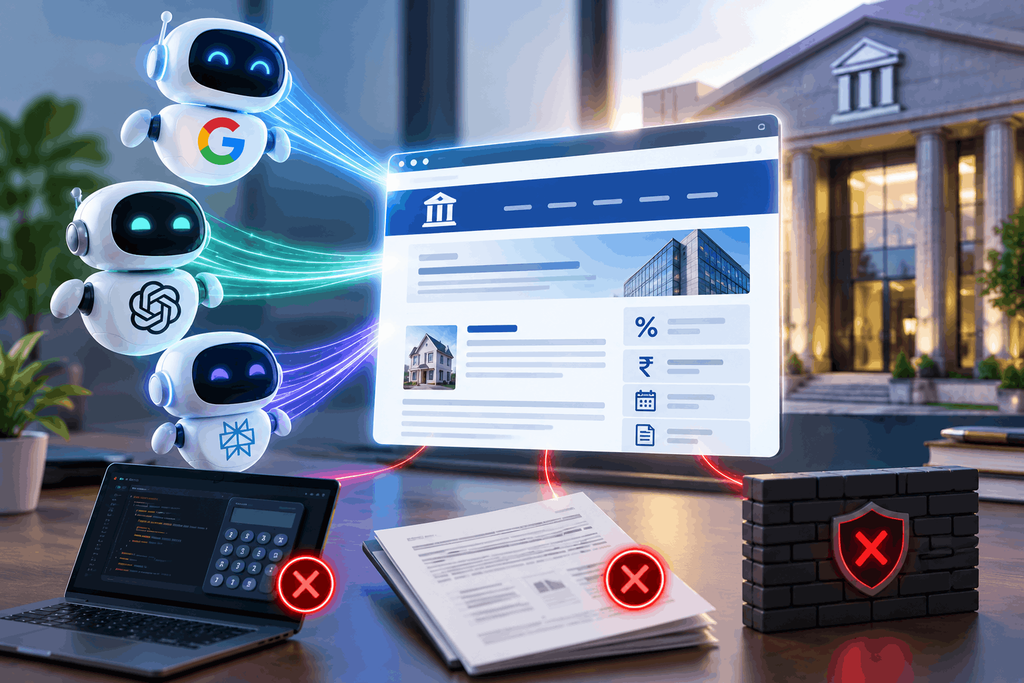
They need the page indexed, crawlable by their search bots, and the key terms present as HTML text. None of them needs special markup to cite you.
Google says a page must be indexed and snippet-eligible to appear in AI Overviews or AI Mode, with no special schema required (Google Search Central). OpenAI uses OAI-SearchBot to surface sites in ChatGPT search, separate from GPTBot, which crawls for model training (OpenAI). PerplexityBot does the same job for Perplexity.
In banks, three things usually break this: rates inside a JavaScript EMI calculator, fees only in a scanned PDF, and a firewall rule that blocks every AI user-agent without separating search bots from training bots.
For the full diagnostic, see my guide to running an AI search visibility audit For product-page work, that is what my AEO/GEO service covers.
Which loan and card pages should a bank fix first?
Start with pages ranking for your highest-volume products, and fix whatever hides the approved numbers. The common situations:
| Situation | What to do | Why |
| Interest rate appears only inside an EMI calculator | Publish the approved rate range and “as on” date as HTML text beside the calculator | Crawlers read page text, not the state of a widget |
| KFS or MITC exists only as a scanned PDF | Add an HTML fee table with the same wording, and link the PDF | A scanned image has no passage to extract |
| Card fees on the product page differ from the MITC | Name one source of truth and one owner; sync the page to it | Contradictory numbers push AI systems towards third-party sources |
| Firewall blocks all AI user-agents | Decide separately on search bots (OAI-SearchBot, PerplexityBot) and training bots (GPTBot) | Blocking a search bot removes you from that engine’s answers |
| Branch Google Business Profiles describe loans differently from the central page | Align profile product and service descriptions with approved central copy | Local answers draw on Google Business Profile as well as your site |
| Customers search in Hindi, Marathi or Tamil | Translate the approved fee table, not the campaign copy | Vernacular queries need a vernacular passage with the same exact terms |
Branch profiles need their own programme: see branch-level local SEO for banks .
How can a bank publish exact terms without creating compliance risk?
Publish what the regulator already requires you to disclose, in the same approved wording, with a date. You aren’t creating new claims; you’re making existing disclosures readable.
For cards, RBI’s Credit Cards and Debit Cards Directions (28 November 2025, replacing the 2022 Master Direction) require a one-page Key Fact Statement with the application, APR quoted for situations such as cash advances, and “the details of all the charges associated with cards” displayed on the issuer’s website (RBI).
For loans, RBI’s circular of 15 April 2024 requires a Key Facts Statement for all new retail and MSME term loans sanctioned on or after 1 October 2024. APR must include all charges, and fees not in the KFS cannot be charged without the borrower’s explicit consent (RBI). The approved numbers already exist. They’re just not on the page.
If the page captures leads through a form or a WhatsApp chatbot, the Digital Personal Data Protection Rules, notified on 14 November 2025 with an 18-month phased timeline, expect consent notices that are standalone, clear and specific about purpose (PIB).
The copy rules I give clients: quote ranges with conditions, date every number, link the KFS or MITC, and drop “lowest” unless compliance can substantiate it. The trade-off is real: exact numbers commit you to an update cadence, and a stale rate quoted by an AI engine is worse than none. Content marketing for regulated products is mostly this discipline.
What goes wrong when large banks try this?
Most failures are about ownership and process, not content. AI visibility for BFSI brands usually stalls in one of five places.
- Approval queues sized for campaigns. A one-line fee update waits behind a festive campaign. Use pre-approved template blocks that change only when the KFS changes.
- Central versus regional ownership. Product owns the page, branch banking owns Google Business Profile, cards owns the MITC. Three owners, three versions.
- Agency handoffs. The agency rewrites copy, compliance rejects it, the page reverts to vague text. Brief agencies from the KFS, not the brand deck.
- Vendor tools. Client-side rate widgets hide text from crawlers. AI visibility trackers sample prompts, so treat their scores as directional.
- Measurement mismatch. Leadership asks for a citation number. Search Console doesn’t report one separately.
How should a bank measure AI citations for loan and card queries?
Use a fixed prompt set tracked monthly, alongside Search Console trends. No single metric exists yet.
Google reports AI Overviews and AI Mode appearances inside the overall “Web” search type in the Search Console Performance report, not as a separate line (Google Search Central). So build 30 to 50 prompts that mirror real customer questions, including Hinglish and vernacular phrasing, covering AI Overviews for bank loan queries and ChatGPT alike. Each month, record whether you’re cited, which URL, and whether the numbers are right.
Accuracy matters as much as presence: a citation quoting an old fee becomes a complaint later. A citation landing on a page nobody can apply from is wasted, which is where conversion rate optimisation and where loan journeys lose applicants come in.
When doesn’t this approach apply?
It works for standardised retail products with published pricing. It is weaker in these cases.
- Fully risk-based pricing. Where loans are priced per borrower, publish the method and range, not a single number.
- Weekly repricing. If rates move weekly and nobody owns updates, publishing numbers adds risk.
- Technical blockers. If pages aren’t indexed or bots are blocked, copy changes do nothing.
- “Which bank is best” queries. AI answers often avoid recommending one lender. You can be cited for facts without being recommended. For comparison searches, see why bank product pages lose to aggregators .
- No guarantees. Google says no special optimisations exist for AI features. This improves odds; it doesn’t buy placement.
Want Your Bank to Stand Out in AI Search?
Improve your visibility across AI-powered search with a focused AI Search SEO strategy.
Get in touch today. No obligation. Contact us today.Your Questions Anwered
Does AI search optimisation for banks need special schema markup?
No. Google states there is no special schema.org structured data required to appear in AI Overviews or AI Mode. A page must be indexed and eligible to show with a snippet. Structured data still helps machines parse your page, but it must match the visible text.
Should a bank block GPTBot?
That is a separate decision from ChatGPT search visibility. OpenAI uses GPTBot for model training and OAI-SearchBot to surface sites in ChatGPT search. A bank can block GPTBot and still allow OAI-SearchBot. Blocking both at the firewall removes the bank from ChatGPT search answers, which is often an unintended side effect of blanket security rules.
Can AI answers show outdated interest rates for my bank?
Yes. AI engines quote what they last retrieved, from your site or from third parties. The practical defence is an “as on” date beside every rate and fee, one source of truth synced to your KFS or MITC, and a monthly check of what AI answers are quoting. Correct your own pages first, since that is what engines recrawl.
Do RBI rules require banks to publish card charges on their website?
RBI’s Credit Cards and Debit Cards Directions, issued 28 November 2025, state that details of all charges associated with cards shall be displayed on the card-issuer’s website, and require APR to be quoted for different situations. Your compliance team should confirm how this applies to your products. This is a description of the rule, not legal advice.
How long before page changes show up in AI answers?
There is no fixed timeline. Changes appear after the relevant search system recrawls the page and the AI answer draws on the updated passage. Track a fixed prompt set monthly rather than expecting movement within days, and confirm in Search Console that the updated page is indexed.
Where to start
This week, take your top credit card page and top personal loan page. Put the KFS or MITC fee lines next to the live copy, list every mismatch or missing number, and send it to compliance as one ticket.
If you want a second pair of eyes on your loan and card pages before the next compliance cycle, get in touch and ask for the free AI visibility scorecard.