Local SEO for banks is won or lost at branch level. A “bank near me” search is decided by the individual branch’s Google Business Profile (its category, hours, reviews and distance from the searcher), not by the brand’s website. Banks that turn branch profiles into leads give each profile an owner, one verified data source and a measured outcome.
Most banks I speak to have done the central work well: the brand site ranks and product pages are approved. Yet a branch in a Tier 2 city still shows the wrong hours and a handful of old reviews.
That gap costs walk-ins, calls and loan enquiries your product pages never see. Across hundreds of branches, it’s a leak no single team feels.
Why do branch profiles matter more than the brand website for “bank near me” searches?
Because Google ranks each branch profile on its own. Your brand’s authority doesn’t pass down to a neglected branch listing.
Google says local results depend on relevance, distance and prominence, and that prominence includes reviews and links (Google Business Profile Help). Distance belongs to the individual location. So “bank near me” is effectively a contest between the branch profiles within a few kilometres of the searcher.
My position: central teams optimise the brand; branch listings nobody owns decide “bank near me”. No brand campaign fixes a branch profile that says “Closed” on a working Saturday. That’s why bank branch local SEO needs its own owner.
Here’s the claim other SEOs will argue with: for these searches, your national domain strength barely matters. In my experience, a smaller bank’s well-kept branch profile regularly beats a bigger bank’s neglected one next door.
What does Google allow banks to do with branch and ATM profiles?
Google allows one profile per branch and a separate profile for an attached ATM, and requires the same name across all locations. Google Business Profile for banks even has its own rule on hours.
The rules that matter, from Google’s Business Profile guidelines:
- Hours: “Banks: Use lobby hours if possible. Otherwise, use drive-through hours.”
- ATMs: “An ATM attached to a bank can use its own separate Business Profile with its own, different hours.”
- Names: “All business locations within the same country must have the same name for all locations.” “[Your Bank] Malviya Nagar” breaks this rule. Keep the location in the address, not the name.
At scale, verification matters. Google’s bulk verification is available for 10 or more locations of the same business, but “agencies with more than one business in one account can’t bulk verify.” The bank should own the organisation account and add vendors as managers, not the other way round.
Who should own each step of a branch profile programme?
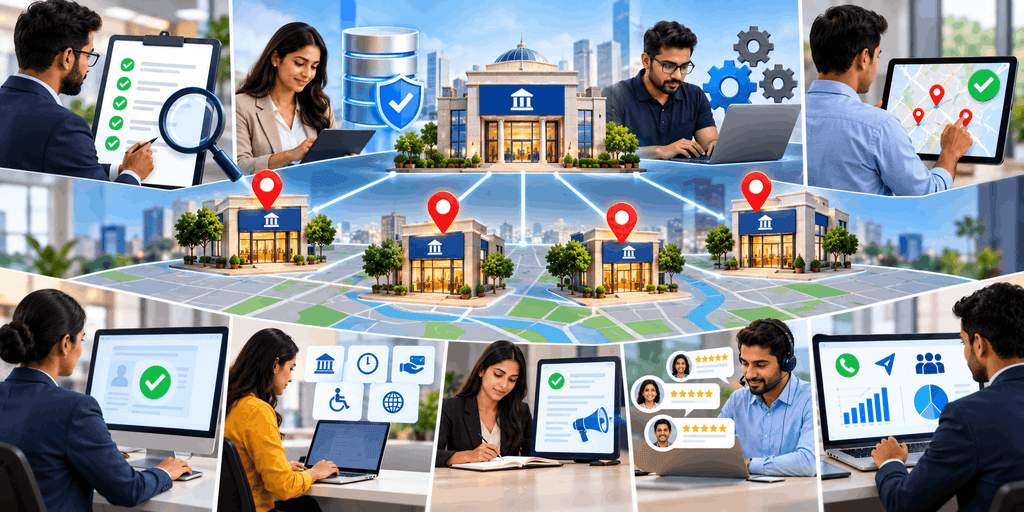
Central owns the data, rules and approvals. Regional teams own local facts and review replies. The vendor owns execution and tooling. Here’s the sequence I use:
- Inventory every listing. Owner: vendor, signed off by central. Include duplicates, unclaimed listings and closed branches still showing as open.
- Name one source of truth. Owner: central. Use the branch master from operations: address, IFSC, lobby hours. Use the IFSC or branch code as the store code so every profile maps to one record.
- Fix structure. Owner: vendor. One profile per branch, the same name everywhere, “Bank” as the primary category, and separate ATM profiles only where the hours differ.
- Claim and verify. Owner: central holds the account; vendor executes. Use bulk verification where eligible, and resolve duplicates before verifying.
- Load local facts. Owner: regional. Services actually offered at that branch (lockers, forex, gold loans), languages spoken, accessibility and state-specific holiday hours. Bank holidays differ by state, so one national upload is wrong somewhere.
- Approve templates once. Owner: central compliance. Pre-approve description templates, post formats and a review-reply library. Branches fill in the variables; they don’t write fresh copy.
- Run reviews properly. Owner: regional. Ask every customer, not only happy ones, and reply from the approved library. More on this below.
- Link each profile to its own branch page. Owner: central web team. Point each profile to a branch page with the address, IFSC, hours and services, tagged with UTM parameters. A link to the homepage throws away both relevance and attribution.
- Report monthly by branch. Owner: central analytics. Calls, direction requests and website clicks per branch, joined to appointments and loan enquiries in your CRM. For what happens after the click, see where loan journeys lose applicants.
Step 6 is where most programmes stall, and it’s what makes the other eight scalable.
Running this as an ongoing programme, not a one-off clean-up, is what my multi-location local SEO for banks and other branch networks covers.
How should branches handle Google reviews without breaking policy?
Ask every customer the same way, never set staff targets, and send complaints to your formal grievance channel.
Google’s review policy prohibits incentives, selectively asking for positive reviews, and “merchants requesting that staff solicit a certain number of reviews.” It also says merchants should not pressure users to leave reviews while on the premises. So a branch-level target of 20 reviews a month is a policy problem, whatever your incentive plan says.
I’d give branch managers reply rights from the approved library rather than routing every reply through head office. Central replies arrive weeks late and read like it.
A negative review is often a complaint. Point the reviewer to your grievance process rather than resolving it in public. Under RBI’s Integrated Ombudsman Scheme, 2026, in force from 1 July 2026, a customer can approach the RBI Ombudsman if the bank hasn’t replied within 30 days, or within any longer timeline set by the applicable guidelines (RBI FAQs).
For reply systems at scale, see my reviews and reputation work.
What can branch profiles say about loans, rates and offers?
Only what’s already approved centrally, in the same wording. Treat a branch post like any other advertisement for the product.
RBI’s circular of 15 April 2024 requires a Key Facts Statement, including an APR computation, for all new retail and MSME term loans sanctioned on or after 1 October 2024 (RBI). If a branch post quotes a rate, it should match the approved central rate that feeds those disclosures. The safe pattern is “home loans from X% p.a., subject to credit assessment, as on [date]”, linked to the central product page.
WhatsApp and appointment forms on branch pages collect personal data. The Digital Personal Data Protection Rules, notified on 14 November 2025 with an 18-month phased timeline, expect consent notices that are “standalone, clear and simple” and explain the specific purpose (PIB).
This is not legal advice. Your compliance team decides what’s permissible.
How do branch profiles show up in AI answers?
AI search tools read the same branch data. AEO/GEO (answer engine and generative engine optimisation) is the work of making your information quotable in AI Overviews and assistants like ChatGPT.
Ask an assistant “which bank near Vaishali Nagar is open on Saturday” and the answer draws on profile data and web pages. Conflicting hours across sources make your branch a risky answer, so a competitor with cleaner data gets named.
This comes from doing steps 2, 5 and 8 properly, not from a separate programme. If AI visibility for product queries is your bigger gap, that’s handled through AEO/GEO for regulated brands, and I cover the product side in how banks get cited in AI answers for loan and card queries.
What goes wrong when large banks run branch-level local SEO?
In my experience, the failures are organisational, not technical.
- Approval delays. Posts and replies queue behind product approvals, so festival hours go live after the festival.
- Central versus local ownership. Users suggest edits to hours and map pins, Google accepts them, and nobody notices because nobody owns the gap.
- Agency handoffs. A new vendor re-claims profiles under its own account. When the contract ends, access goes with it.
- Vendor tools. A listing tool with stale data overwrites branch corrections on every sync.
- Measurement mismatch. Digital reports profile views; branch banking tracks accounts opened. Without a CRM join, neither trusts the other’s numbers.
When doesn’t this branch-level approach apply?
It’s the wrong priority in four situations.
- You have few branches. A co-operative bank with eight branches needs a tidy checklist, not a governance programme.
- Your growth is digital-first. If most accounts open through the app, product-page SEO and AI answers pay back faster. I explain why bank product pages lose to aggregators and what to target instead.
- Branches can’t absorb demand. More calls to a branch that doesn’t pick up damage your reviews.
- Your branch master data is wrong. Fix it first, or you spread the error to hundreds of profiles.
For how the map pack weighs these signals in India, see my breakdown of map pack ranking factors in India.
Want Better Local SEO for Your Bank?
Improve local visibility and help customers find your branches easily.
Contact us today. No obligation. 👉 Talk to Our SEO ExpertsFrequently asked questions
What is local SEO for banks in India?
Local SEO for banks is the work of making each branch and ATM rank and convert in Google Maps and local search. It covers accurate Google Business Profiles, lobby hours, reviews, branch pages on the bank’s website and branch-level reporting. The unit of competition is the individual branch profile, because Google ranks local results partly on distance from the searcher.
Should each bank branch have its own Google Business Profile?
Yes. Google’s guidelines support one profile per physical branch, and say an ATM attached to a bank can have its own separate profile with different hours. All locations in the same country must use the same business name. Put the locality in the address, never in the name, to avoid suspension risk.
Can a bank ask customers for Google reviews at the branch?
Yes, if every customer is asked the same way. Google’s review policy prohibits incentives, selectively asking happy customers, asking staff to collect a set number of reviews, and pressuring people to review while on the premises. A neutral request after service, such as a QR code on a counter card, fits within those rules.
Who should own Google Business Profiles in a large bank?
The bank should own the organisation account centrally and add agencies or vendors as managers. Central teams own location data, templates and compliance approval. Regional or branch teams own local facts and review replies. Vendors execute. This protects access when vendor contracts change and keeps one source of truth.
How do banks measure leads from Google Business Profiles?
Track calls, direction requests and website clicks per branch in Business Profile performance reports. Point each profile to a branch-specific page with UTM tags, then join those sessions to appointments, account openings or loan enquiries in the CRM. Report monthly by branch and by region so leadership sees enquiries, not only views.
Where to start
This week, export your branch master and your Google Business Profile location list. Match them on branch code or IFSC. Count three things: branches with no profile, profiles with no matching branch, and profiles whose hours differ from the branch master. That count is your business case.
If you want a second pair of eyes on your multi-location Google Business Profile audit, get in touch.